- An actively managed certificate (AMC) is a debt security whose value tracks a portfolio run at the discretion of a named strategy manager, issued with its own ISIN and settled like a bond.
- An AMC can be issued directly by a bank or through a bankruptcy-remote special purpose vehicle, typically a securitisation compartment.
- An SPV-issued AMC can generally be brought to market in days rather than months, at a lower cost than a bank platform or a full fund launch.
- Setup and ongoing costs for an AMC typically run roughly an order of magnitude below a comparable regulated fund.
- AMCs settle through SIX SIS, Euroclear or Clearstream, are generally structured for professional investors, and can be listed on a venue such as the Vienna MTF for added transparency.
An asset manager with a strategy worth packaging has traditionally faced a choice between two unsatisfactory routes. A regulated fund brings a board, a depositary, a regulator and months of preparation before the first subscription. A managed account avoids that weight but leaves every client holding a separate portfolio, with no single instrument that a private bank can book, price and report on.
The actively managed certificate, or AMC, sits between the two. It wraps an active strategy into one tradeable, ISIN-bearing security that settles through the same infrastructure as a bond and can be held in any standard custody account. For investors, the appeal is simple access to active management. For the manager bringing the certificate to market, the more useful questions are how an AMC is structured, who needs to be involved and what it costs to issue and run.
What is an actively managed certificate?
Structurally, an AMC is a debt security whose value tracks a portfolio managed at the discretion of a named strategy manager. It is issued with its own ISIN and settled through the international infrastructure used for bonds, typically SIX SIS, Euroclear or Clearstream.
Two features set it apart. Compared with an ordinary bond, the underlying exposure moves: the strategy manager can rebalance, rotate or hedge the portfolio within an agreed mandate, and the certificate's value follows those decisions. Compared with a fund, the wrapper differs. An AMC is issued as a single security rather than as units in a collective investment scheme, which keeps the regulatory and administrative burden far lighter. It belongs to the wider family of structured products, alongside the passive tracker certificate, from which it differs mainly in the discretion given to the manager.
Bank-issued vs SPV-issued AMCs
There are two established ways to bring an AMC to market, and the right choice depends largely on how much control the strategy manager wants over the process.
In the bank-issued model, an investment bank issues the certificate on its own balance sheet and becomes the counterparty to investors. The route carries strong institutional recognition and ready-made distribution through the bank's network. It also tends to mean a longer onboarding process, higher minimum ticket sizes and issuer credit risk concentrated entirely in one institution.
In the SPV-issued model, the certificate is issued by a bankruptcy-remote, off-balance-sheet special purpose vehicle, often a compartment within a Luxembourg securitisation vehicle. The manager gains real control over its counterparties, including the custodian, broker and calculation agent, and time to market is typically measured in days rather than months, at a lower cost than either a bank platform or a full fund launch.
Neither route is universally better. A bank-issued AMC suits a manager who wants an established institutional name behind the certificate. An SPV-issued AMC suits a manager who values speed, cost efficiency and a say over who else sits in the structure.
The parties to an AMC
Whichever route is chosen, the same core roles must be filled.
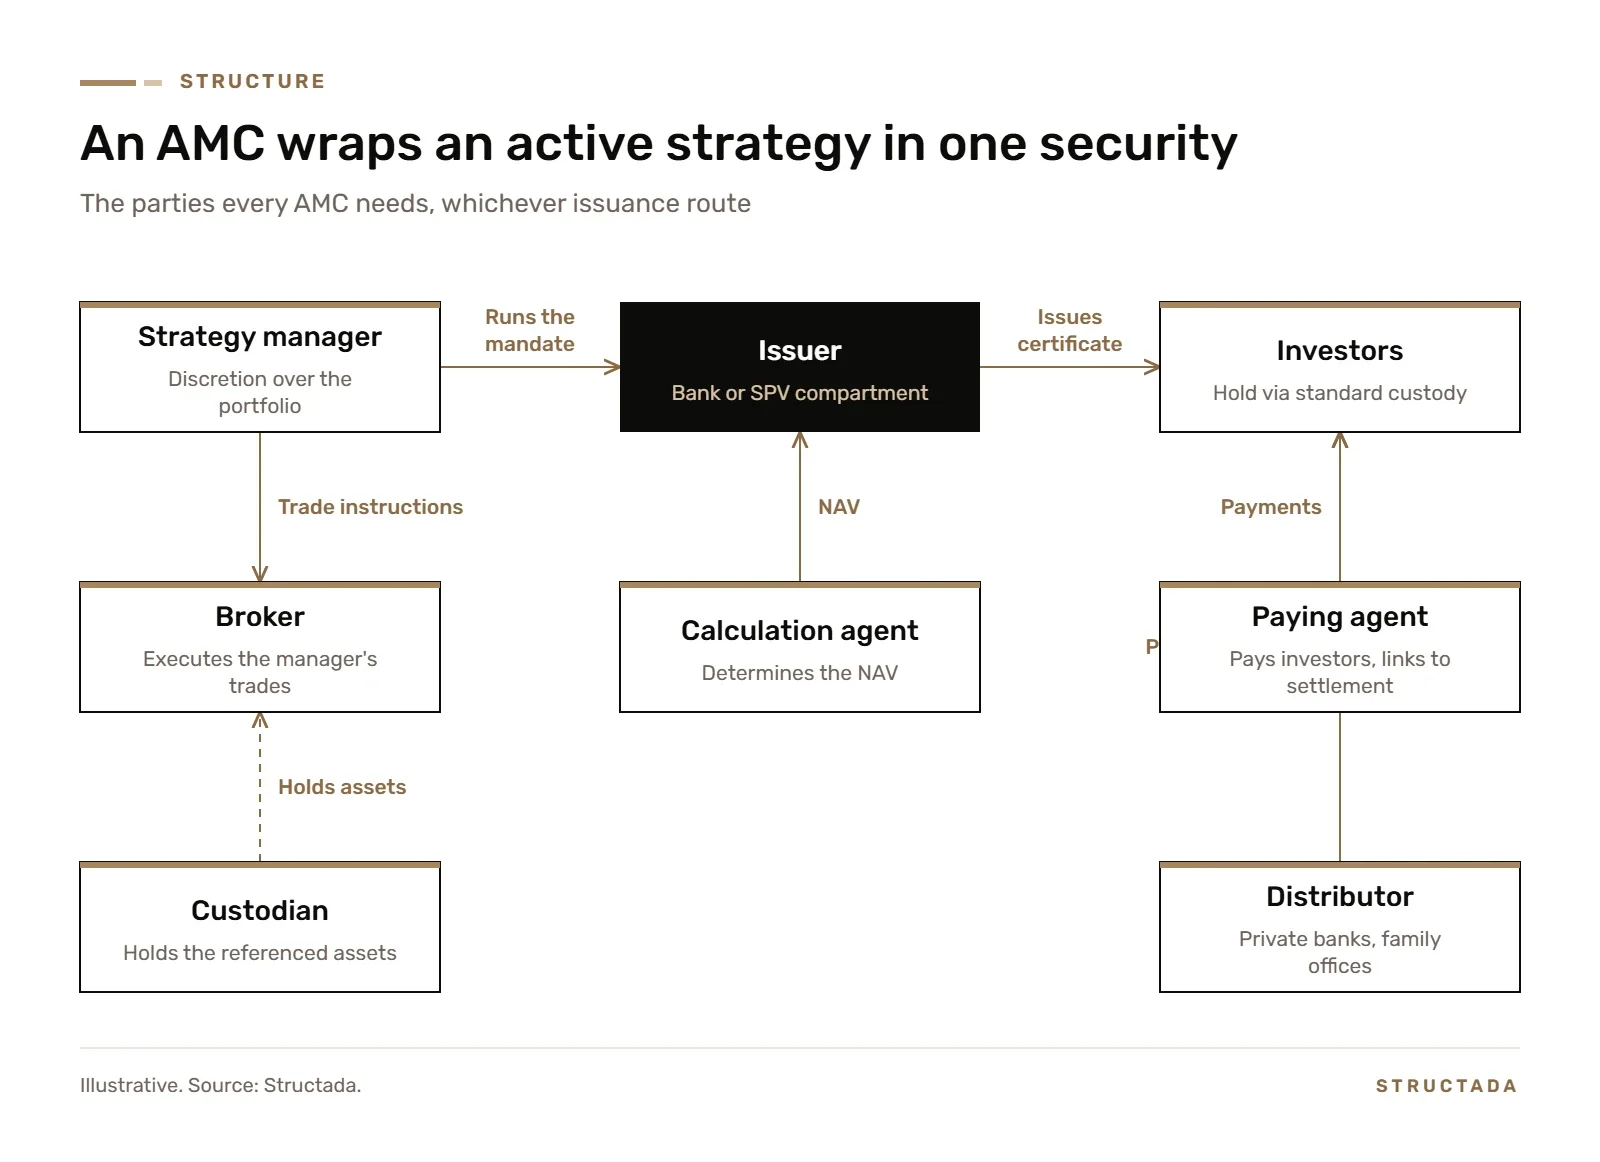
The issuer, whether a bank or an SPV, legally issues the certificate and bears the obligation to investors. The strategy manager holds discretionary control over the underlying portfolio and makes the trading decisions. A calculation agent determines the certificate's net asset value on an ongoing basis, which is what investors and their custodians rely on for pricing.
Around them sit the operational functions. The paying agent handles payments to investors and coordinates with the settlement system. The custodian holds the assets referenced by the certificate, and the broker executes the strategy manager's instructions in the market. Finally, a distributor places the certificate with investors, typically private banks, family offices or professional platforms.
How AMC issuance works
Bringing an AMC to market follows a consistent sequence.
- Define the mandate: the strategy, eligible assets and risk limits.
- Choose the issuance route and appoint the calculation agent, paying agent, custodian and broker.
- Draft the term sheet and governing documentation, including NAV calculation and redemption terms.
- Obtain the ISIN and connect the certificate to SIX SIS, Euroclear or Clearstream.
- Open for subscription, close and strike the first NAV.
- Administer the certificate through to maturity or early termination.
The mandate is the foundation. Once the certificate is live, the documentation governs how it behaves, so ambiguity at this stage becomes a dispute later. During the life of the certificate, the strategy manager runs the portfolio while the calculation agent, paying agent and custodian handle subscriptions, redemptions, corporate actions and reporting. Termination follows the terms agreed at launch, whether at a scheduled maturity or on an early termination event. Our guide to AMC issuance covers the practical steps in more detail.
The cost of structuring and running an AMC
Cost is one of the clearest advantages an AMC has over a fund launch. Setting one up through an SPV typically covers establishing the compartment, onboarding the paying agent, arranging custody and obtaining the ISIN. The all-in setup cost generally comes in roughly an order of magnitude below what a comparable fund launch would require.
Ongoing costs cover administration, valuation, the paying agent, custody and audit. These scale far more lightly than the compliance infrastructure a regulated fund must carry, which matters most for strategies that start small and grow. For managers comparing the options more broadly, our guide to alternatives to setting up a fund sets out where the certificate fits.
Listing and distribution
Because most AMCs settle through SIX SIS, Euroclear or Clearstream, they can be held through standard custodian bank relationships without special onboarding on the investor's side.
Some issuers also list the certificate on a recognised venue, such as the Vienna MTF, for the transparency a listing provides. An unlisted certificate with a live ISIN can still be distributed and held normally. Distribution generally runs through the channels used for other structured products: private banks, family offices, external asset managers and professional investment platforms.
Regulation and governance
An AMC is generally intended for professional investors and structured as a securitised wrapper rather than a regulated collective investment scheme, which is what keeps its regulatory footprint lighter than a fund's. A lighter footprint makes documentation discipline more important, since the documents carry most of the protection that regulation would otherwise provide.
Eligibility criteria for the underlying assets, the boundaries of the manager's mandate and the mechanics of NAV calculation all need to be settled clearly at the outset, much as they would be for a credit linked note. Where the certificate is issued through an SPV, counterparty risk must also be assessed at the level of each service provider, from custodian to broker to calculation agent, rather than resting on a single bank's balance sheet.
What this means for issuers
For a manager weighing how to take a strategy to market, the AMC is now a mature and widely understood instrument. The real decision is which issuance route fits the strategy, the investor base and the timetable. A bank platform offers institutional weight and distribution at the price of control and speed. An SPV compartment offers speed, cost efficiency and the freedom to choose the counterparties, at the price of the manager taking more responsibility for how the structure is assembled.
The managers who get the most from an AMC treat it as a piece of capital markets infrastructure rather than a marketing wrapper. They draft the mandate tightly, choose a calculation agent and custodian whose reporting their distributors already trust, and agree the settlement and listing arrangements before launch.
Frequently Asked Questions
What is an actively managed certificate?
A debt security whose value follows a portfolio that a named manager runs actively, giving investors one ISIN-bearing instrument rather than units in a fund.
What is the difference between an AMC and a fund?
An AMC is a single security issued by a bank or an SPV, while a fund is a collective investment scheme in which investors hold units or shares. The AMC carries a lighter regulatory burden but exposes investors to issuer credit risk.
Who can issue an AMC?
Either a bank, acting as the direct issuing counterparty, or a special purpose vehicle, typically a securitisation compartment, acting as an off-balance-sheet issuer.
How long does it take to structure an AMC?
A bank-issued AMC can take considerably longer because of the bank's internal approvals. An SPV-issued AMC can generally be launched within days once documentation and counterparties are in place.
Is an AMC regulated in the same way as a fund?
No. An AMC is generally structured as a securitised wrapper for professional investors rather than a regulated collective investment scheme, which keeps its costs well below a comparable fund.
How is an AMC strategy manager paid?
Through management and performance fees built into the certificate, with the returns of the underlying strategy flowing into the certificate's value.