- Most credit linked notes are issued over the counter by private placement, yet they rely on the same institutional infrastructure as listed bonds for identification, settlement and custody.
- An ISIN, settlement through Euroclear or Clearstream and visibility on Bloomberg are what allow a private bank, family office or institution to book and hold a note.
- The choice between Euroclear and Clearstream is usually driven by investor jurisdiction and custodian preference, and many programmes use both.
- CLNs reach professional investors through private banks, family offices, institutional allocators, discretionary managers and adviser platforms, often in response to a specific investor mandate.
- For issuers, the quality of the settlement chain and of the counterparties around a note has a direct bearing on how widely it can be held and at what cost.
A credit linked note can be impeccably structured and still struggle to find a home. The reason is rarely the credit. It is usually that the note cannot be booked by the investor's custodian, priced by their systems or held alongside the rest of their portfolio. For a professional investor, a security that sits outside that chain is an operational problem before it is an investment decision.
That is why the question of how credit linked notes reach investors deserves as much attention as how they are structured. Most CLNs are sold privately, but they travel through the same institutional infrastructure as any international bond: an identifier, a clearing system, a custodian and a paying agent. Understanding that chain explains which investors a note can reach, and why some notes are far easier to hold than others.
What is CLN distribution?
Once a credit linked note is structured and priced, it has to be issued, settled and allocated to investors. Unlike listed equities or benchmark bonds, most CLNs are issued over the counter through a private placement, sold to a defined group of professional investors rather than offered to the market at large.
Private does not mean informal. The note still needs to be identifiable, transferable and capable of being held in custody, in exactly the way a listed bond would be. Distribution, in this sense, is the combination of that infrastructure and the placement relationships that connect a note to the investors whose mandates it fits.
How a credit linked note reaches an investor
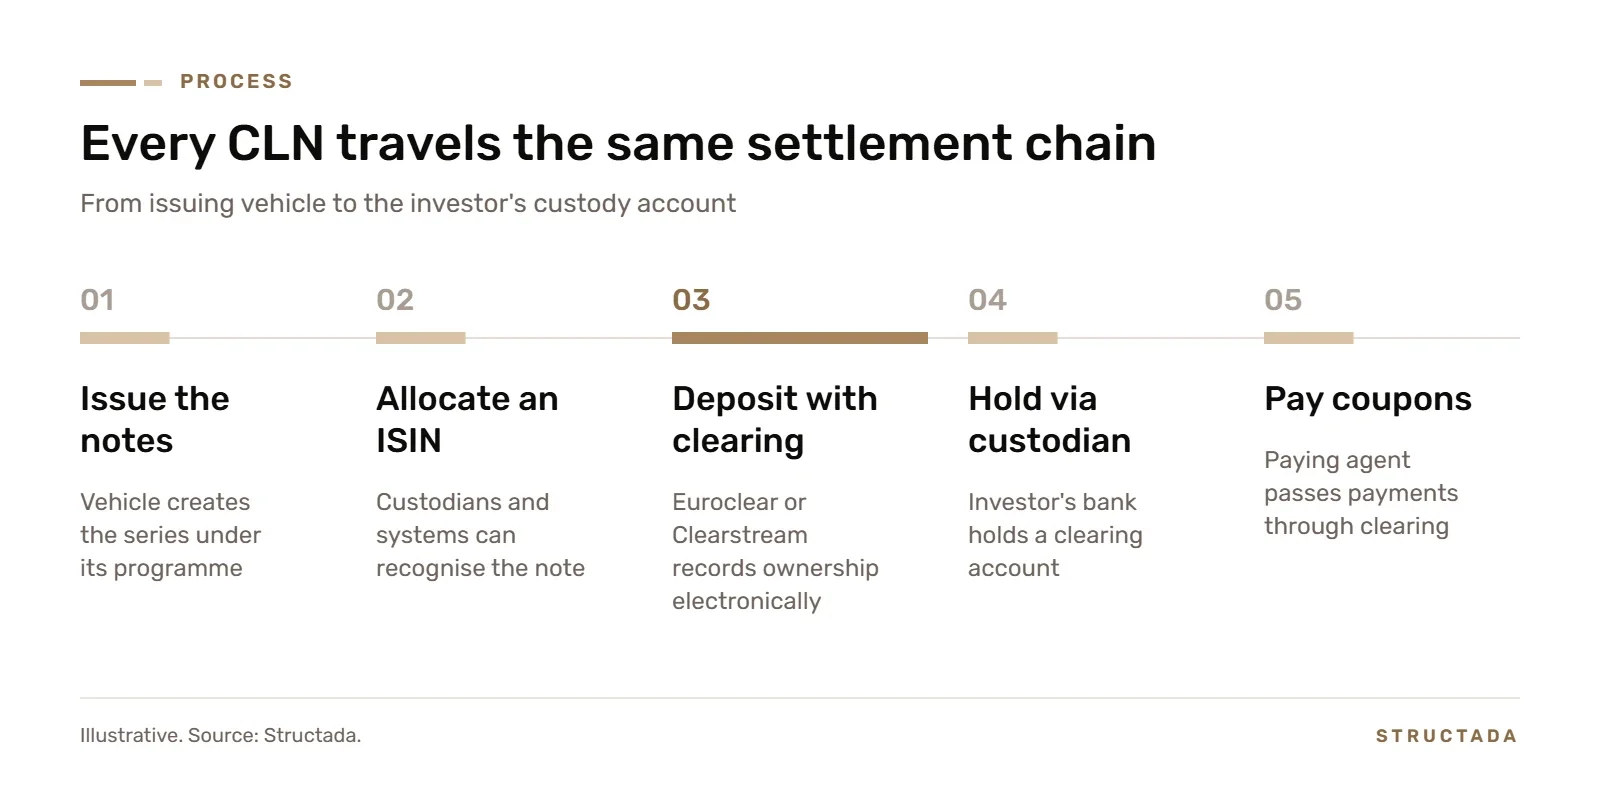
The chain begins with issuance. The issuing vehicle creates the notes under its programme documentation, and each series is allocated an ISIN, the international identifier that custodians, trading systems and portfolio reporting tools use to recognise a security. Without one, most custodians cannot book a note and most institutional investors cannot hold it.
The notes are then deposited with a clearing system, which records ownership electronically and allows the notes to move between accounts against payment. Investors hold their position through their own bank or custodian, which in turn holds an account with the clearing system. A paying agent collects coupons and principal from the issuer and passes them through the clearing system to each holder on the payment date. The practical steps are set out in our Euroclear-ready checklist.
Bloomberg and CLN pricing
Bloomberg remains the main interface through which professional investors find and assess credit linked notes. A new series can be set up on Bloomberg's bond screens under its ISIN, giving investors a single place to see the coupon structure, maturity and underlying credit exposure, with the full term sheet available on request.
That visibility matters more than it might appear. Investment committees, compliance teams and portfolio systems all expect to see a security described in a standard way before an allocation is approved. A note that appears on Bloomberg with clean static data can be compared with alternatives, priced in the investor's own systems and reported to clients without manual workarounds.
Euroclear and Clearstream
Most credit linked notes settle through Euroclear, one of the two international central securities depositories. Euroclear provides the settlement and custody infrastructure for international debt, allowing an institution in Luxembourg, London or Singapore to book, settle and hold the same note on the same terms. Settlement through Euroclear also opens the note to the private banks and discretionary wealth managers whose custody chains run through it.
Clearstream, part of Deutsche Börse Group, performs the same role. Euroclear tends to dominate across Western Europe and the UK, while Clearstream is often preferred by institutions in Germany, Switzerland and parts of Asia. The choice usually comes down to investor jurisdiction, custodian preference and operational cost, and many CLN programmes use both depending on where a given group of investors sits. The two systems are linked, so a note eligible in one can generally be held by participants of the other.
Listing a credit linked note
Listing is optional for a privately placed CLN, but many issuers choose it. Some investor mandates permit only listed securities, and a listing on a recognised exchange can matter for tax purposes, including the quoted Eurobond exemption from UK withholding tax. Venues such as the Vienna MTF, Euronext Dublin and TISE are commonly used for professional investor debt. A listing widens the range of investors whose rules allow them to hold the note, although on its own it does little for liquidity.
Who invests in credit linked notes
Credit linked notes are sold only to professional investors, and they reach them through a consistent set of channels. Private banks, particularly those with discretionary portfolio management teams, use CLNs as fixed income alternatives. Family offices and investment managers hold them directly. Institutional allocators, including credit funds and insurance groups, buy them for defined credit exposure. Independent advisers, external asset managers and wealth advisers with eligible clients reach them through professional platforms, and discretionary managers allocate a portion of client assets to credit strategies through them. Our guide to accessing the wealth channel looks at that segment in more depth.
Investor eligibility rules vary by jurisdiction. In the Gulf, for example, the definitions used by the UAE's regulators determine who may be offered a note, as our guide to professional investor status in the UAE explains.
Reverse enquiry and primary placement
Many CLNs begin with the investor rather than the issuer. Under reverse enquiry, a specific mandate, such as a five-year fixed note yielding 10% or more against European credit risk, prompts the structuring of a note built to match it. In other cases the process runs the other way: a lender uses a CLN to convert an illiquid portfolio into a security that can then be placed with the investors described above.
In practice, good distribution works from both directions at once. It starts from what return, risk and duration investors are actually seeking, and from the real funding needs of the lender or originator, and it builds a note where the two meet.
What this means for issuers
For an issuer, the settlement chain is part of the product. The credibility of the ISIN, the clearing system the note settles through, the quality of the paying agent and administrator and the transparency of reporting all shape how many investors can say yes, and on what terms. A note that a private bank's custodian cannot book will be declined regardless of its credit merits.
The practical lesson is to design for the investor's operations from the start. Deciding the clearing system, listing venue and reporting standard at term sheet stage, alongside the vehicle and the documentation, avoids discovering late in the process that the intended investors cannot hold the note. Issuers moving from loan agreements to notes will find the wider comparison in credit linked notes vs bilateral loans.
Frequently Asked Questions
How do investors buy a credit linked note?
Through their bank, broker or custodian, which buys the note by its ISIN and holds it in Euroclear or Clearstream alongside the rest of the portfolio.
Does a credit linked note need an ISIN?
In practice, yes. Without one, most custodians cannot book the note and most institutional investors cannot hold it.
Can a credit linked note be listed?
Yes, though it is optional. Many issuers list on a recognised venue such as the Vienna MTF for investor mandates and tax reasons.
What is the difference between Euroclear and Clearstream?
Both are international central securities depositories. Euroclear is more common in Western Europe and the UK, while Clearstream is often preferred in Germany, Switzerland and parts of Asia.
What is reverse enquiry?
A process in which an investor's specific requirements for return, risk and maturity prompt the structuring of a note to match them.
Who can invest in credit linked notes?
Professional investors, such as family offices, private banks, wealth managers and institutions.