- A private credit fund assumes pooled, committed money and a strategy that evolves over time; a credit linked note assumes a defined, bounded exposure known at the outset.
- Credit linked notes let an issuer fund a defined portfolio or lending programme without committing to a fund's regulatory and governance burden before the strategy justifies it.
- CLN documentation fixes risk at the outset through eligibility criteria, cash-flow priorities and triggers, while fund governance relies on continuing oversight.
- Funds scale vertically as one vehicle grows larger; CLNs scale horizontally through further note issues and syndication.
- Many managers use CLNs as a stepping stone to a fund, building a track record and investor confidence before a permanent vehicle is warranted.
As private credit strategies mature, most of the managers running them reach the same point. Investor interest is growing, the strategy is proving itself, and the lending book needs more funding to grow. What is less clear is the structure that funding should take.
For non-bank lenders, credit platforms and emerging managers, the choice usually narrows to two options: issuing credit linked notes or launching a private credit fund. Both are established institutional routes, and both can support sophisticated strategies. They are built, however, for different moments in a strategy's life, and the decision between them turns less on ambition than on timing.
The core difference between a CLN and a private credit fund
The most important difference lies in what each structure assumes at the outset.
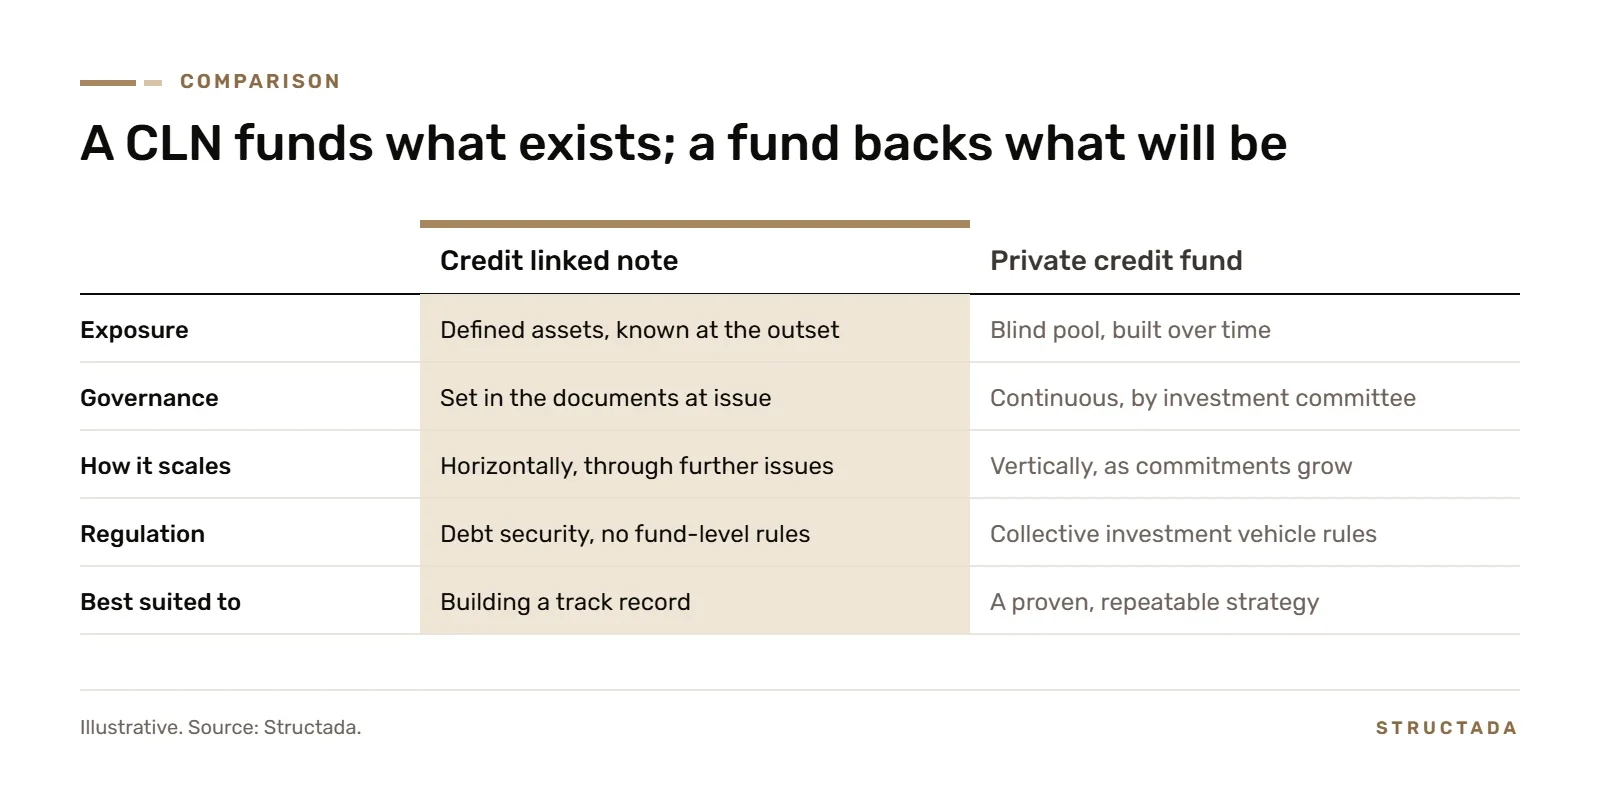
A private credit fund assumes permanence. Investors commit money before deployment is complete, assets are pooled rather than referenced individually, and investors accept that they are backing a strategy that will develop over time. Governance, reporting and regulation are all designed around that pooled, forward-looking model.
A credit linked note assumes definition. Funding is provided against a specific credit exposure or a clearly bounded lending programme, and investors know what they are financing, how cash flows behave and how risk is managed. The structure is built around existing activity rather than future discretion.
Neither assumption is better in isolation. What matters is which one matches the strategy as it stands today.
Control and timing for issuers
For issuers, the decision is usually driven by control and timing more than cost. Launching a fund is a significant commitment. It brings regulatory requirements, service providers, continuing governance and a permanent vehicle that has to be justified by scale. For managers with deep pipelines and repeatable deal flow, that commitment makes sense. For others, it can be premature.
Credit linked notes allow a manager to fund a strategy without locking it into a fund structure too early. Notes can be issued against a defined portfolio, a lending book or a specific programme, with terms set by how the assets actually behave rather than by how a fund is expected to operate. That flexibility suits non-bank lenders and credit platforms whose balance sheets and origination volumes change quickly, because the funding structure can move with the business rather than forcing the business to conform to the structure.
Blind pools and defined exposure
From the investor's side, the contrast matters just as much. Private credit funds typically involve blind-pool exposure. Investors commit before the assets are fully identified and rely on the manager's discretion, governance and track record to manage that uncertainty. For many institutional allocators, that is an accepted and well-understood trade-off.
Credit linked notes remove much of the uncertainty by design. The exposure is defined at the outset, and the documentation specifies which assets are referenced, how cash flows are applied and how losses are treated. Investors are underwriting credit performance rather than future decision-making.
A CLN carries no less credit risk than a fund for that reason; the underlying credit risk is the same either way. What changes is how clearly that risk is described before an investor commits. For professional investors allocating across several private credit strategies, that clarity often makes CLNs easier to assess and easier to hold alongside other structured credit.
Governance in each structure
Both structures can be governed well, but governance takes a different form in each.
In a fund, governance is continuous. An investment committee approves transactions over time, and concentration and leverage limits are monitored as the portfolio changes. Investor protection depends on that oversight and the processes behind it.
In a credit linked note, governance is largely set at the outset. Asset eligibility criteria are fixed in the documentation, cash-flow priorities are set out in advance, and trigger mechanics define how underperformance is addressed. Once the structure is live, its behaviour is constrained by those documents rather than by ongoing discretion. For issuers, that front-loaded discipline reduces the risk of later renegotiation and helps the structure behave consistently through a full credit cycle. For investors, it offers confidence that terms will not drift as conditions change.
Scale and syndication
Funds and credit linked notes both scale, but in different directions.
Funds scale vertically. As commitments grow, the same vehicle becomes larger, which works well when deployment pipelines are deep and diversified and money is expected to stay committed for long periods.
Credit linked notes scale horizontally. Further notes can be issued on identical terms, allowing new investors to participate without reshaping the underlying structure, and exposure can be segmented by vintage, geography or strategy without creating parallel funds. Because CLNs are securities, they also lend themselves to syndication. They can be issued in standard denominations, settled through recognised clearing systems and held in custody alongside other debt instruments, which reduces operational friction as the investor base broadens. For strategies whose funding needs grow in stages rather than all at once, this form of scalability is often the more practical.
Regulation and structural commitment
Private credit funds are collective investment vehicles, subject to fund-level regulation, marketing restrictions and the investor protections that suit pooled products. That adds complexity, but it also provides a framework institutional allocators already know how to work with.
Credit linked notes are debt securities. When issued through an established framework such as a Luxembourg securitisation vehicle, they can be distributed to professional investors without being classified as a collective investment scheme. The issuer operates within a robust legal regime while avoiding fund-level obligations, and for issuers reaching cross-border professional investors, that difference can materially affect speed, cost and flexibility.
When a private credit fund is the right answer
None of this argues against private credit funds. For many managers, a fund is the natural destination. Once a strategy is proven, pipelines are consistent and investor demand is repeatable, a fund offers efficiency, permanence and scale. It lets the manager concentrate on portfolio construction rather than individual exposures, and gives investors' money a long-term home.
In practice, many successful managers use credit linked notes as a stepping stone between bilateral loans and a fund rather than as a permanent alternative. The notes allow a track record to be built, governance to be demonstrated and investor confidence to develop, and the fund follows once the strategy has earned it. For managers weighing a Luxembourg fund in particular, our comparison of CLNs and RAIFs sets out the trade-offs.
What this means for issuers
Credit linked notes and private credit funds serve different stages of a strategy's life rather than competing for the same one. A CLN funds a defined exposure with embedded discipline and room to scale through further issues. A fund pools commitments for long-term deployment once the strategy is mature enough to justify a permanent vehicle.
The managers who get the most from either structure are those who match it to the strategy as it stands, not as they hope it will become. Defaulting to whichever structure is most familiar is the commonest mistake. The better question is which problem the business is solving today, and when it will be time to move from one structure to the other.
Frequently Asked Questions
What are private credit funds?
Pooled vehicles that take commitments from investors and lend them out over time, run by a manager who chooses the loans. Investors usually commit before the portfolio is known.
What is the difference between a credit linked note and a private credit fund?
A CLN gives investors exposure to a defined set of assets through a note. A fund pools money across a portfolio built over its life, with more continuing regulation and governance.
What are the two main types of private credit?
Direct lending to companies, and asset-based finance secured on receivables, loan books or real assets.
Is a credit linked note a collective investment scheme?
No. When issued through a Luxembourg securitisation vehicle, a CLN is a debt security and can be distributed to professional investors without fund-level regulation.
Can an issuer move from CLNs to a fund later?
Yes. Many managers use CLNs to build a track record and investor base, then launch a fund once scale justifies the cost.